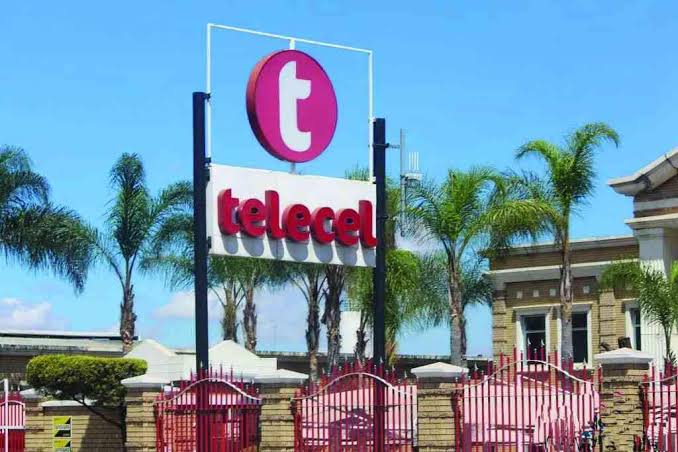
Zimbabwe’s telecommunications industry could be approaching a significant ownership and investment transition following a proposed US$175 million acquisition and corporate rescue of Telecel Zimbabwe by investment vehicle Augustus Capital. The transaction, structured around the financially distressed mobile network operator’s ongoing corporate rescue proceedings, offers a potential route to recapitalisation, network modernisation and the restoration of competition in a market increasingly dominated by Econet Wireless and NetOne.
However, beyond the headline investment figure lies a more complicated corporate restructuring involving more than US$240 million in reported liabilities, a collapsing subscriber base, substantial regulatory obligations and the challenge of rebuilding a telecommunications network that has lost much of its competitive relevance.
For Augustus Capital, the opportunity is to acquire and rehabilitate a strategic telecommunications asset. For Zimbabwe, the implications extend beyond a change in ownership: the outcome could influence mobile connectivity, digital financial services, infrastructure investment and the competitiveness of the country’s wider digital economy.
The critical question is whether the proposed transaction can translate financial commitments into a commercially sustainable telecommunications business.
A distressed operator with strategic value
Telecel Zimbabwe was once a significant competitor in the country’s mobile telecommunications industry. At its peak, the operator competed aggressively for subscribers and established a nationwide presence through voice, data and mobile financial services.
Its fortunes subsequently deteriorated following years of financial pressure, ownership changes and inadequate network investment. The departure of international shareholder VimpelCom in 2015 marked an important turning point. The Zimbabwean state subsequently acquired the business through its investment structures, but the change in ownership did not produce the sustained capital investment required to maintain network competitiveness.
The consequences became increasingly apparent in the operator’s market performance.
According to the Postal and Telecommunications Regulatory Authority of Zimbabwe’s fourth-quarter 2025 sector report, Telecel had 303,284 active mobile subscriptions at the end of December 2025, compared with 305,042 in the preceding quarter. By comparison, Econet had 12.37 million active subscriptions, while NetOne had approximately 4.10 million.
The figures illustrate the scale of Telecel’s competitive disadvantage. Its subscriber base had contracted substantially from its historical peak, leaving the operator with a marginal position in a market that continues to expand.
The problem is not simply a shortage of customers. Zimbabwe’s demand for mobile connectivity, internet access and digital services continues to grow. Rather, Telecel’s challenge has been its diminishing ability to convert that demand into subscribers and sustainable revenue because of deteriorating infrastructure, limited network capacity and declining customer confidence.
The company was placed under voluntary corporate rescue in October 2025, with Grant Thornton Zimbabwe’s Kundai Tibugare and Bulisa Mbano appointed as corporate rescue practitioners.
The process was intended to provide a structured alternative to liquidation, allowing the company to address its liabilities while preserving the possibility of operational recovery.
Augustus Capital’s US$175 million proposition
The proposed transaction places Augustus Capital at the centre of Telecel’s restructuring.
The investment vehicle was established specifically to participate in the corporate rescue process and acquire a controlling interest in the mobile network operator.
According to details of the proposed rescue plan reported in July and August 2026, the transaction carries a headline value of US$175 million and is supported by a financing arrangement of up to US$127 million from Ecobank.
The proposed funding is conditional on the formal adoption of the corporate rescue plan. It is intended to support the acquisition and provide operational capital for the company’s recovery.
The financing proposition is accompanied by arrangements with telecommunications equipment manufacturer ZTE and Satewave Technologies.
These arrangements reportedly include US$60.5 million in network equipment supplies and US$28.5 million in network rollout services. A broader capital expenditure programme of approximately US$89 million is envisaged for network modernisation.
The proposed infrastructure programme includes a large-scale fourth-generation (4G) and Long-Term Evolution (LTE) deployment, with approximately 1,200 sites targeted.
The investment is designed to address one of Telecel’s most significant structural weaknesses: the gap between its existing network infrastructure and the capabilities of its competitors.
The proposed rollout is expected to take approximately 12 months, with an initial six-month period allocated to equipment manufacturing, shipping and delivery, followed by a further six months for network deployment.
This is an ambitious programme. Its success will depend on financing availability, procurement execution, site acquisition, power infrastructure, regulatory coordination and the ability to deploy equipment across the country within the projected timeframe.
Importantly, a financing facility is not the same as capital already disbursed, while contractual equipment arrangements do not establish that infrastructure has been installed. The distinction will be central to evaluating the transaction’s actual progress.
Restructuring ownership and settling legacy liabilities
The proposed acquisition also involves a fundamental restructuring of Telecel’s ownership.
The existing shareholding structure has historically involved state interests through ZARNet, under the Mutapa Investment Fund, and Empowerment Corporation, a local shareholder consortium.
Reporting on the proposed transaction indicates that Augustus Capital intends to acquire the existing Empowerment Corporation stake and obtain control through the restructuring, while existing shareholders collectively retain a minority interest.
The reported rescue-plan terms offer nominal consideration of US$1 to Mutapa Investment Fund and US$0.50 to Empowerment Corporation for their existing equity interests. Existing shareholders are also expected to retain a combined 15% interest in the restructured business.
These nominal payments should not be interpreted as the full economic value of the transaction. The proposed settlement of shareholder-related loans and the retention of minority equity interests form part of the wider restructuring arrangements.
There have, however, been inconsistencies in published accounts of the precise ownership percentages. The historical 60% state-related and 40% Empowerment Corporation structure is reported in the more detailed analysis of the rescue plan, while some subsequent reporting describes a different allocation. The final adopted plan and signed transaction documents will be necessary to establish the definitive post-transaction shareholding.
The liabilities present an equally important dimension.
Telecel is reported to owe creditors more than US$240 million. These obligations include historical shareholder loans, regulatory fees, equipment supplier claims, trade creditors and other liabilities.
The proposed rescue plan seeks to restructure these obligations rather than require immediate settlement in full.
Under the reported terms, unsecured trade creditors could recover approximately 40 cents for every US dollar owed, while shareholder-related loans of approximately US$97.7 million are proposed for compromise at seven cents in the dollar.
Historical licence-fee arrears owed to POTRAZ are also subject to a restructuring arrangement. The reported proposal provides for seven cents in the dollar on historical arrears, with future licence fees to be settled in full through instalments over approximately eight years following a one-year grace period.
The overall estimated recovery for the regulator is approximately 61 cents in the dollar.
These arrangements illustrate the central purpose of corporate rescue: balancing the interests of investors, creditors, employees and regulators while attempting to preserve the underlying economic value of a distressed enterprise.
For creditors, the proposition is that a restructured and operational Telecel could generate better recoveries than liquidation. For the prospective investor, the opportunity lies in acquiring control of a strategically valuable business while negotiating a manageable financial and operational starting point.
The competitive challenge
Telecel’s proposed rescue comes at a time when Zimbabwe’s telecommunications market is becoming increasingly data-driven.
Mobile connectivity is no longer principally about voice calls and SMS. Consumers and businesses increasingly depend on mobile internet for digital payments, e-commerce, remote work, financial services, education, entertainment and access to public services.
This shift has changed the economics of telecommunications investment.
Operators must continuously invest in network capacity, spectrum utilisation, fibre connectivity, power resilience and customer experience. A network that cannot provide reliable data services risks losing relevance regardless of its historical brand recognition.
POTRAZ’s first-quarter 2026 industry statistics demonstrate the scale of this transformation. National mobile data consumption increased by approximately 11.9% to 179 petabytes during the quarter, while active internet subscriptions rose to approximately 13.92 million.
Yet Telecel’s position within this expanding market remained weak.
Reporting on the regulator’s first-quarter statistics indicated that Telecel’s mobile data traffic declined by 15.98% to approximately 149.04 million megabytes, even as national mobile data consumption increased.
Econet, by comparison, recorded mobile data traffic growth of approximately 20.14%, reaching 156.4 billion megabytes.
The contrast is particularly significant. It demonstrates that the market is expanding, but the benefits of that expansion are not being distributed evenly among operators.
For Augustus Capital, rebuilding the network is therefore only the first stage of the turnaround.
The company will also need to persuade customers to return to Telecel, develop competitive data packages, improve customer service and establish a differentiated commercial proposition.
Its competitors have advantages that extend beyond network infrastructure. Econet has an established subscriber ecosystem, extensive distribution and integrated financial services through EcoCash. NetOne benefits from its national infrastructure footprint and established public-sector presence.
Telecel will have to compete against these established businesses while simultaneously funding its own recovery.
The challenge is considerable, but not necessarily insurmountable. A revitalised operator could pursue opportunities in enterprise connectivity, fixed wireless broadband, wholesale infrastructure, rural connectivity and specialised data services.
Its mobile money platform, Telecash, could also become part of a broader digital-services strategy, provided it receives the necessary investment, regulatory compliance and commercial repositioning.
What the rescue could mean for Zimbabwe’s digital economy
The survival of a third mobile network operator has implications beyond the fortunes of one company.
Competition in telecommunications can influence service pricing, network investment, geographical coverage and the pace of technological innovation.
A financially stronger Telecel could create additional competitive pressure on established operators, particularly if it successfully introduces differentiated data packages and reliable connectivity.
For businesses, the benefits could include more options for enterprise connectivity, improved negotiating power and additional infrastructure partnerships.
Small and medium-sized enterprises could benefit from more affordable mobile data and improved access to digital payment platforms, online marketplaces and cloud-based services.
In rural and underserved communities, network investment could help bridge connectivity gaps and support agricultural information services, digital financial inclusion and access to education.
The proposed deployment of approximately 1,200 network sites is therefore significant. If implemented effectively, it could contribute to expanding telecommunications infrastructure and improving service availability.
There is also an investment dimension.
Zimbabwe’s digital economy requires substantial capital to develop telecommunications infrastructure, data centres, fibre networks and other supporting systems. The participation of private investment vehicles and international financing institutions in distressed infrastructure assets could demonstrate the potential for structured capital to rehabilitate commercially viable businesses.
However, the broader economic benefits will depend on the actual scale and geographical distribution of investment rather than headline commitments alone.
Employment and the wider corporate rescue question
Telecel’s restructuring also has implications for employment and Zimbabwe’s corporate rescue framework.
The reported proposal provides for the retention of all 248 existing employees, with approximately US$1 million set aside to meet potential unforeseen retrenchment costs arising from future restructuring.
This is important in an industry where technical expertise, network maintenance, customer support and distribution capabilities are essential to operational recovery.
The proposed retention of employees also illustrates the potential economic value of corporate rescue as an alternative to liquidation.
Under Zimbabwe’s Insolvency Act [Chapter 6:07], corporate rescue provides a framework through which financially distressed companies can attempt to reorganise their operations, liabilities and ownership while continuing business activities.
Telecel’s case will test the practical effectiveness of this framework in a strategically important sector.
A successful restructuring could demonstrate that distressed infrastructure businesses can attract new investment and preserve economic value even after prolonged financial deterioration.
Conversely, failure would raise difficult questions about the ability of corporate rescue proceedings to resolve complex ownership, financing and operational problems in capital-intensive industries.
The risks that could undermine the turnaround
Despite the scale of the proposed investment, Telecel’s recovery is far from guaranteed.
The first risk concerns financing execution.
The reported Ecobank facility of up to US$127 million is conditional on adoption of the corporate rescue plan. The availability of the facility, its drawdown conditions and the timing of actual disbursements will determine whether the proposed investment programme can proceed.
The second risk is execution.
A nationwide network modernisation programme involving approximately 1,200 sites requires extensive logistical coordination. Equipment procurement, site development, electricity supply, backup power, fibre backhaul and regulatory approvals can introduce delays and increase costs.
The third risk is market recovery.
Telecel must rebuild customer confidence in a market where subscribers have already migrated to competitors. Network coverage alone will not guarantee customer acquisition. Service reliability, pricing, distribution and customer experience will determine whether subscribers return.
The fourth risk concerns governance and strategic management.
The involvement of Augustus Capital and the proposed partnership with a major regional telecommunications operator could provide access to capital and technical expertise. However, the identity and operational responsibilities of the regional partner have not been clearly established in the reporting reviewed.
The final ownership structure, management arrangements and allocation of decision-making responsibilities will be important determinants of long-term performance.
There is also the question of licence continuity and regulatory compliance. The proposed business model assumes continued operation under Telecel’s existing telecommunications licence. The investor will need to satisfy all relevant regulatory requirements, including obligations relating to spectrum, licence fees, infrastructure deployment and service quality.
What investors and the market should watch
The next phase of Telecel’s story should be measured through implementation rather than announcements.
Several developments will provide a more reliable indication of whether the rescue is succeeding.
First, creditors and shareholders must formally adopt the corporate rescue plan in accordance with the applicable legal requirements, with the necessary regulatory and transactional approvals secured.
Second, the Ecobank financing facility must progress from a reported commitment to actual funding availability and disbursement.
Third, the proposed network rollout should be accompanied by measurable milestones, including the number of sites upgraded, geographical coverage improvements and the introduction of reliable 4G services.
Fourth, POTRAZ’s quarterly industry reports should provide evidence of subscriber recovery and improving data traffic. These indicators will offer an independent measure of whether Telecel is regaining market relevance.
Finally, the proposed strategic partnership with a regional telecommunications operator should be clarified. Access to experienced technical and commercial management could be as important as the capital itself.
The market will also need clarity on the final ownership structure, creditor settlements and the implementation timetable.
A strategic opportunity, but execution will determine the outcome
Augustus Capital’s proposed US$175 million Telecel transaction represents a potentially significant opportunity to rehabilitate one of Zimbabwe’s most important telecommunications assets.
The proposal combines acquisition financing, debt restructuring, network investment and the prospect of strategic operational partnerships. If successfully implemented, it could restore Telecel as a meaningful competitor, preserve employment and expand the infrastructure supporting Zimbabwe’s digital economy.
But the scale of the financial commitment should not obscure the depth of the operational challenge.
Telecel is not simply a company requiring fresh capital. It is an operator that must rebuild its network, regain customers, restore commercial credibility and compete against businesses that have spent years strengthening their infrastructure and digital ecosystems.
The distinction between acquiring a distressed telecommunications licence and rebuilding a competitive telecommunications company is fundamental.
For Zimbabwe, a successful turnaround could strengthen market competition and demonstrate the capacity of private capital to rehabilitate strategic infrastructure. For Augustus Capital, it represents an opportunity to create value through the restructuring of a distressed but strategically positioned enterprise.
The outcome will ultimately depend on whether the proposed financing becomes deployable capital, whether infrastructure commitments translate into functioning networks and whether customers see sufficient reason to return.
Telecel’s next chapter will not be determined by the size of its rescue package, but by the quality and discipline of its execution.