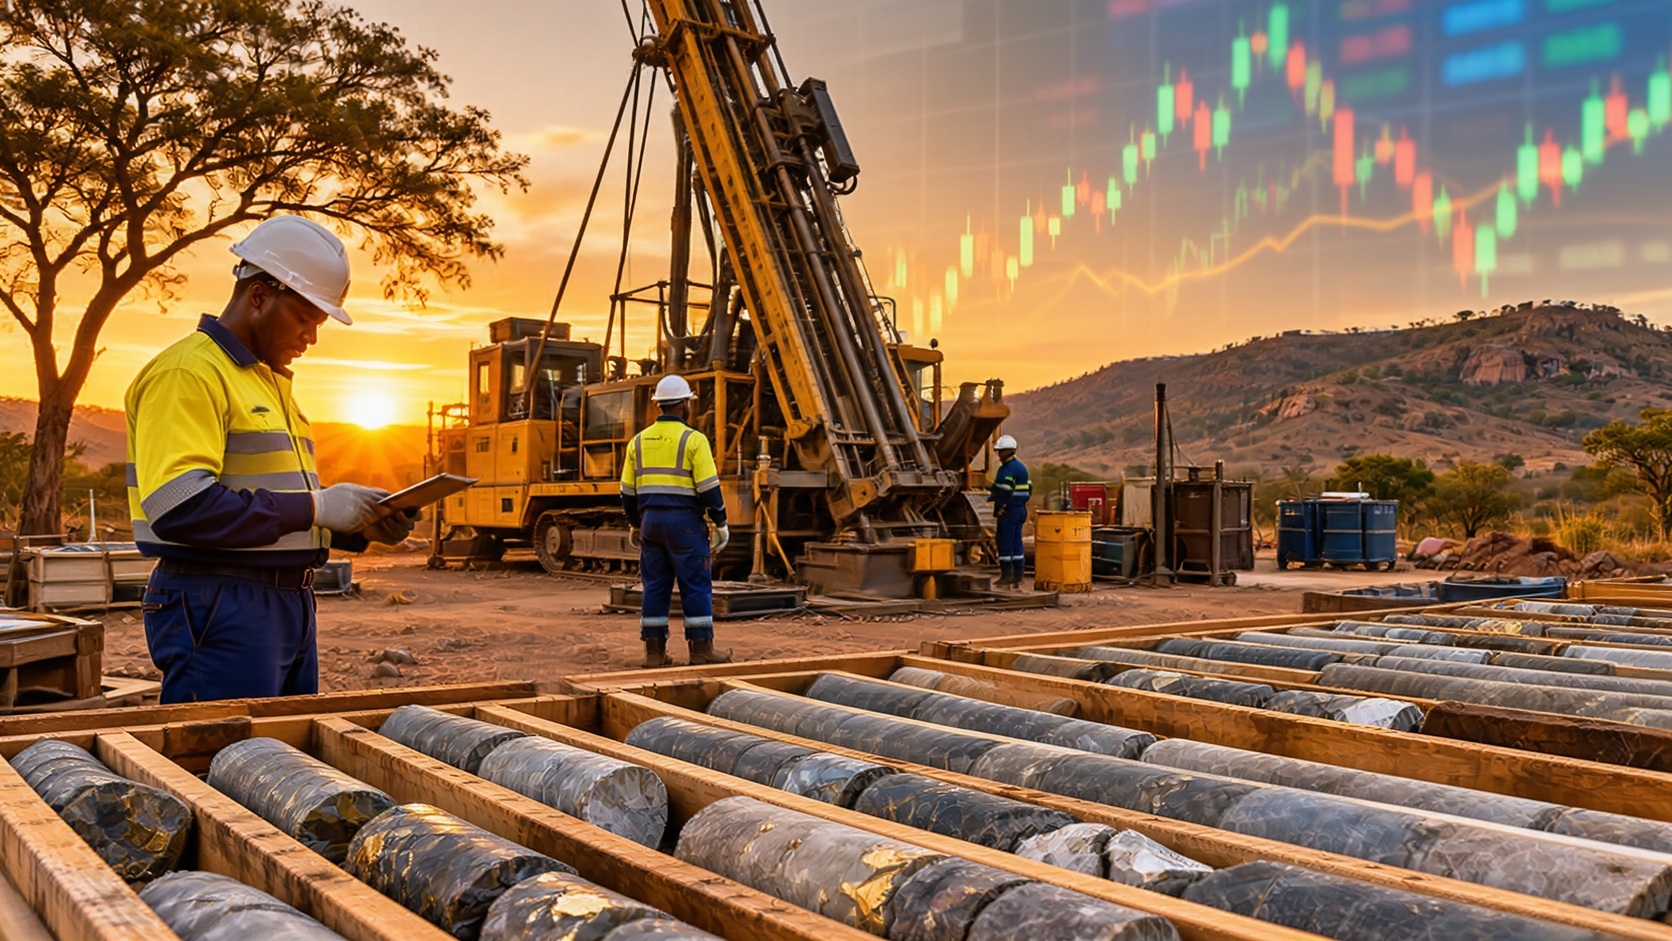
Gold is now Zimbabwe’s most important source of foreign currency, and 2026 is on course to be a record year. The central question for investors and policymakers is whether this earnings surge is a one-off price effect or the start of a more durable shift in the mining economy.
Background
Export receipts have climbed sharply over two years. One industry analysis puts 2025 gold export earnings at about US$4.38 billion, against US$2.25 billion in 2024, growth of roughly 94.6%. Another report puts the 2025 total at a record US$4.61 billion, driven by favourable global prices and increased artisanal mining. The two estimates differ, and the RBZ’s final audited figure should be treated as the reference.
The monthly pattern in 2026 has been strong but uneven. January receipts were US$498.3 million, February US$549 million, March US$406.1 million, April about US$528 million and May US$503.3 million. June was the strongest month at US$597.1 million.
Key Developments
Price is the main driver. In August, Zimbabwe’s average realised export price reached US$4,676.82 per ounce, producing monthly receipts of US$417.48 million. Price is not the whole story, though. One analysis says the government has pushed small-scale and informal miners to sell through the state buyer rather than smuggle gold abroad. Output was about 50 tonnes in 2025, and Treasury expects 55.6 tonnes in 2026.
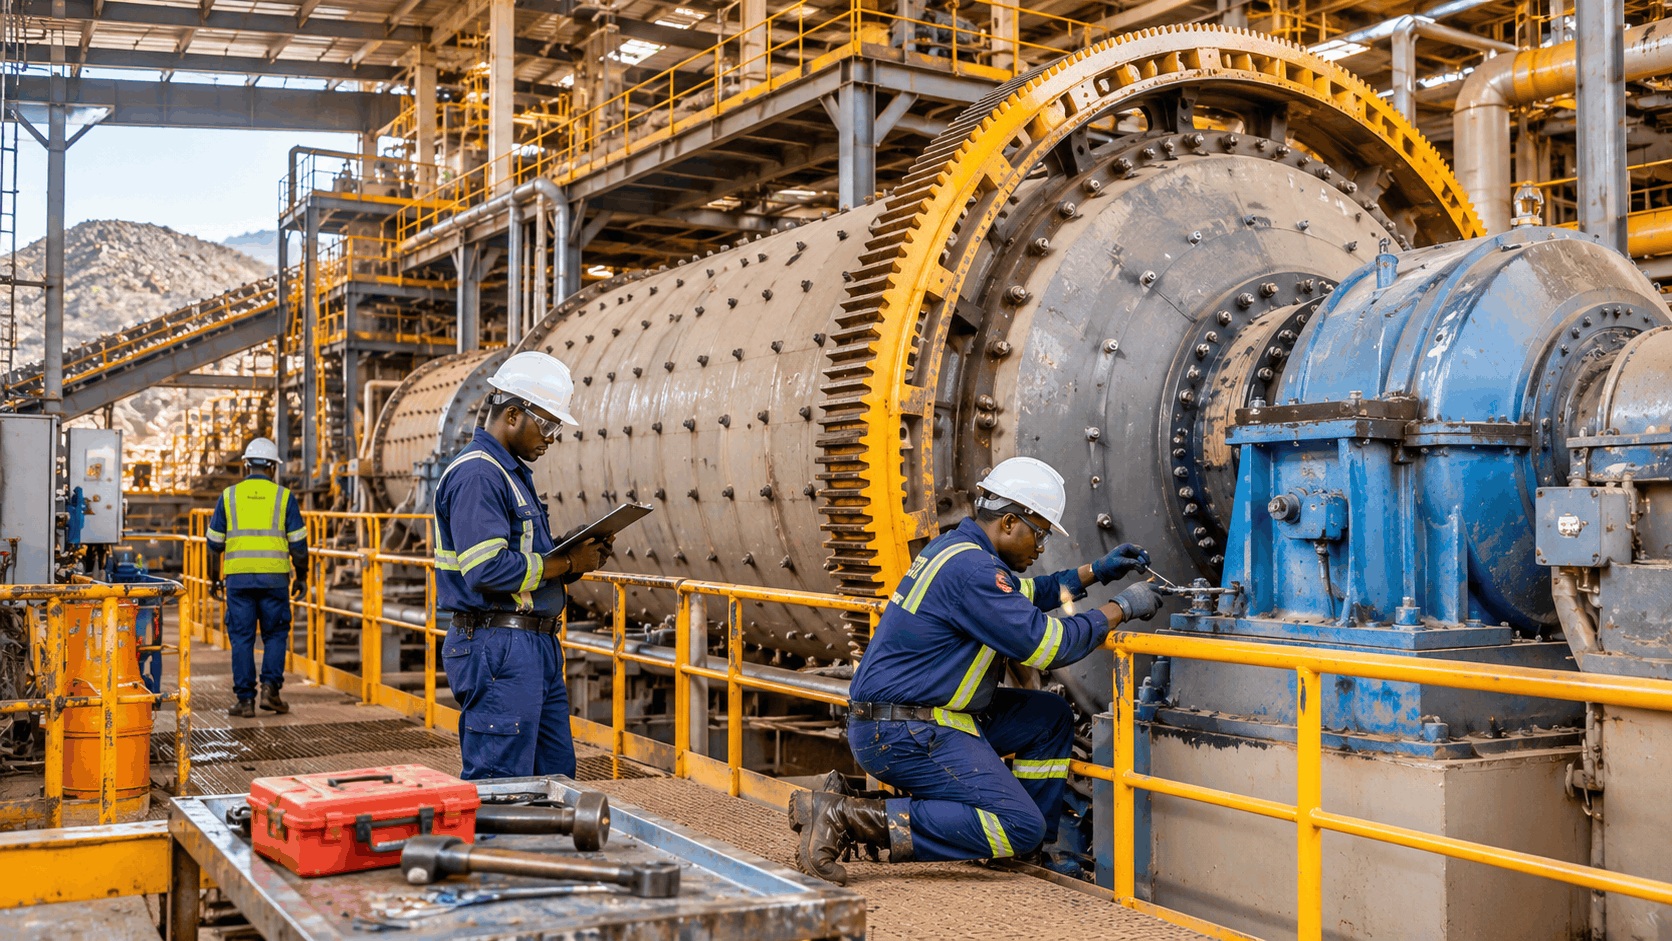
Deliveries are rising. Zimbabwe channelled 26.05 tonnes of gold through Fidelity Gold Refinery in the first seven months of 2026, more than halfway to its 50-tonne annual target. That figure is a physical-volume measure. The US$3.84 billion valuation attached to those deliveries is a gross market value at average international prices, not actual export receipts.
The year-end target. The wider ambition is to raise annual mining export earnings to US$5 billion through higher production, formalisation of artisanal and small-scale mining and investment in processing infrastructure. Official projections cited in local reporting anticipate output above 55 tonnes and gold export earnings of US$5bn.
Investment is following. Eleven Zimbabwean banks committed US$160 million towards Mutapa Gold Resources’ US$240 million Shamva Hill expansion in November 2026, and Kavango Resources has a pilot processing plant under way. Domestic bank financing of a mining expansion is notable because it suggests local lenders are now willing to back sector projects.
Data Discrepancies Readers Should Know About
The figures reported in the market do not fully reconcile, and The Business Diary has not been able to resolve the differences from the sources available:
- First-half total: RBZ-sourced reports give about US$3.1bn. Other media, citing RBZ mid-year materials, report gold earnings of US$3.82 billion in the first half. The gap may reflect different definitions (for example, receipts versus gross export value).
- Five-month figure: One report puts January–May earnings at a record US$3.071bn, with May alone at US$1.158bn. That sits awkwardly with the monthly series above, where May is about US$503m and the six-month total is about US$3.1bn.
- Nine-month figure: Gold earnings were reported at US$2.95bn for January to September, up 53% on US$1.93bn a year earlier. That is lower than the six-month total in other reports, so the series cannot all be on the same basis.
Until the RBZ publishes a reconciled series, the US$3.1bn first-half figure should be read as an indicative RBZ-sourced estimate, and year-to-date comparisons should be made with care.
Business Implications
Foreign currency and the ZiG. Gold is one of the reserve assets backing the Zimbabwe Gold (ZiG) currency, so higher earnings and official deliveries give the Reserve Bank more scope to strengthen its gold reserves over time. Currency stability is the benefit most directly felt by SMEs, which depend on predictable import costs and pricing.
Formalisation. Part of the surge reflects gold moving from informal channels to official ones. That raises recorded earnings, and it also widens the tax base and brings small-scale miners closer to formal finance.
Spillovers. Mining equipment, logistics, assaying, security, catering and accommodation firms gain from higher activity. The benefit to SMEs is real but not automatic. It depends on local procurement and on how quickly miners are paid.
Industry Analysis
The 2026 earnings surge is better understood as a price event layered on a policy shift than as a structural transformation. Value addition is the test of transformation. Exporting doré or semi-refined gold captures only part of the value chain, while refining, processing and downstream services keep more of it in-country. The Shamva Hill financing and the pilot processing plants point in that direction but remain early-stage.
The sector also carries risks that the headline numbers hide:
- Price dependence. Earnings that nearly tripled in a year can fall just as quickly if bullion prices retreat.
- Monthly volatility. The swing between a very weak and a very strong month in some reports shows how lumpy deliveries and receipts can be.
- Artisanal sector formalisation. Sustaining official deliveries requires prompt, competitive payment to small-scale miners. Otherwise informal channels regain appeal.
- Regulatory and environmental pressure on small-scale operations, which account for a significant share of output.
Market Outlook
If prices stay near recent levels and output reaches the Treasury’s projected 55.6 tonnes, 2026 would be another record year. The more consequential question is 2027 and beyond: whether producers expand capacity, whether processing investment translates into higher in-country value, and whether foreign currency inflows are converted into lasting reserves and productive investment, not just consumption.
Conclusion
The US$3.1bn first-half gold figure confirms that mining is the engine of Zimbabwe’s foreign-currency economy. Whether it transforms the mining economy depends on what follows: refining capacity, supply-chain linkages and policy discipline when prices eventually cool.
Our Analysis
Record earnings and structural change are different things. The first can be delivered by a strong price, the second only by investment in processing, finance and supplier networks. For SMEs, the practical opportunity lies in the supply chain around mines, not in the headline export figure.
What’s Next?
Watch for the RBZ’s reconciled monthly series, full-year 2026 deliveries against the 50-tonne target, progress at Shamva Hill and the processing projects, and any change in how small-scale miners are paid.