Mining & Minerals
Zimplats Hands Over to Segula as Mhembere Retires After 19 Years and Two Directors Join the Board
Zimplats Holdings, one of Zimbabwe’s largest platinum producers, changed its chief executive and added two independent directors on 1 November 2026. The company says the CEO handover is designed to preserve continuity. The test now is whether the new leadership can deliver on a capital programme that has run for years.


Mining & Minerals
Zimbabwe’s Lithium Strategy and the Economics of Mineral Beneficiation
Discover how Zimbabwe’s lithium export ban and mineral beneficiation policies are driving record GDP growth, attracting billions in investment, and reshaping its economic future.
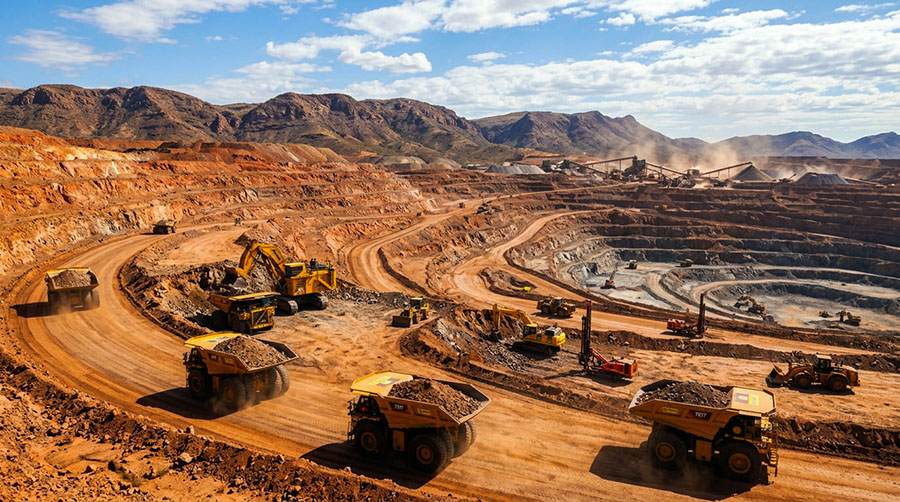
Zimbabwe’s drive to process lithium domestically marks a decisive shift in its mineral policy. But turning geological wealth into lasting economic prosperity will depend on reliable electricity, adequate refining capacity, investment discipline and a more equitable distribution of mining revenues.
By Richard Tentone
The Geological Imperative: From Extraction to Industrialisation
Zimbabwe’s mineral wealth has long underpinned its economic fortunes, with gold, platinum group metals (PGMs), chrome and other minerals playing a central role in export earnings and investment. Its lithium deposits, however, are increasingly reshaping the country’s mining landscape and industrial ambitions.
From Arcadia in Mashonaland East and Bikita in Masvingo to Kamativi in Matabeleland North and Sandawana in the Midlands, Zimbabwe possesses significant lithium resources that have attracted substantial international investment. The expansion of lithium mining has positioned the country as an important participant in the global battery-materials supply chain, driven by demand for electric vehicles, energy storage systems and renewable energy technologies.
Yet the economic significance of lithium extends beyond the volume extracted from the ground. The more consequential question is how much value Zimbabwe can retain after extraction.
For years, the conventional mining model relied heavily on exporting mineral commodities at relatively early stages of processing. Although this generated foreign currency and supported employment, a substantial share of the value created through advanced refining, chemical conversion and battery-material manufacturing accrued elsewhere.
This arrangement exposed a structural weakness in the country’s mineral economy: possessing valuable resources does not automatically translate into industrial development.
Zimbabwe’s lithium beneficiation policy seeks to address this imbalance. By requiring mining companies to process lithium domestically, the government aims to capture a greater share of the value chain, stimulate industrial investment, create skilled employment and strengthen the link between mineral extraction and broader economic development.
The strategy is consistent with the country’s Vision 2030 ambitions, under which mineral resources are expected to support industrialisation, infrastructure development and rising national incomes.
The challenge is translating that ambition into a commercially sustainable industrial ecosystem.
The Regulatory Shift: From Raw Ore Exports to Chemical Processing
Zimbabwe’s lithium beneficiation framework has evolved through a series of regulatory interventions designed to restrict the export of increasingly unprocessed mineral products.
A major milestone came in December 2022 with Statutory Instrument 213 of 2022, the Base Minerals Export Control (Unbeneficiated Lithium Bearing Ores) Order, made under the Base Minerals Export Control Act [Chapter 21:05].
The measure restricted exports of unbeneficiated lithium-bearing ores without the required ministerial authorisation. Its practical effect was to encourage investment in domestic processing, particularly crushing, concentration and other preparatory operations.
Subsequent regulatory measures sought to establish technical requirements for exported concentrates and strengthen oversight of mineral exports.
The policy direction became more ambitious as the government moved towards a prohibition on lithium concentrate exports, with lithium sulphate identified in the supplied policy framework as the required next stage of domestic processing.
The distinction is important. Concentrating lithium-bearing ore improves the mineral content of the material, but it does not complete the chemical conversion required to produce lithium compounds for downstream battery-material applications. Lithium sulphate represents a more advanced stage of processing, although additional conversion and refining may still be necessary before the material can enter particular battery-manufacturing processes.
Zimbabwe’s policy is therefore not simply about processing ore before export. It is an attempt to move the mining industry further up the industrial value chain.
The changing policy framework
The following chronology summarises the policy trajectory.
| Policy milestone | Strategic objective | Implication for the mining industry |
|---|---|---|
| December 2022: S.I. 213 of 2022 | Restrict exports of unbeneficiated lithium-bearing ore | Encourage domestic ore preparation and concentration |
| 2023: Subsequent regulatory measures | Strengthen concentrate specifications and export oversight | Improve compliance and mineral-value reporting |
| February 2026: Reported export suspension | Restrict exports of unrefined minerals and lithium concentrates | Accelerate domestic processing investment |
| April 2026: Reported transitional quota arrangements | Provide temporary export allowances under specified conditions | Give qualifying producers time to develop processing capacity |
| 1 January 2027: Stated policy deadline | End lithium concentrate exports and require further domestic processing | Shift producers towards chemical conversion or approved third-party processing |
The effectiveness of this framework will ultimately depend on the consistency of its implementation, the availability of processing infrastructure and the ability of different classes of mining companies to comply.
The February 2026 Acceleration: Industrial Ambition Meets Commercial Reality
The supplied account identifies an acceleration of export restrictions in February 2026, followed by transitional export arrangements in April. These developments, if confirmed in their stated form, would represent a significant intensification of Zimbabwe’s beneficiation strategy.
The rationale for tighter controls is understandable. Mineral exports must be accurately declared, royalties and taxes must be collected, and strategic minerals should not leave the country through illicit channels. Effective oversight is also essential to maintaining public confidence that the country is receiving a fair return from its natural resources.
However, the economic consequences of an abrupt export restriction depend on the readiness of domestic processing facilities.
A producer that already operates a chemical refinery can respond differently from a smaller operator that has neither the capital nor the technical capacity to construct one. Large, well-capitalised mining companies may be able to finance new plants, secure engineering contractors and negotiate long-term supply agreements. Smaller producers may face working-capital shortages, rising storage costs and uncertainty over their ability to sell output.
This creates a potential divide within the mining industry.
The policy may accelerate investment among major operators while simultaneously placing smaller producers under considerable financial pressure. If processing capacity remains concentrated in a limited number of large companies, junior miners could become dependent on third-party facilities and the commercial terms offered by their owners.
That dependence would introduce another question of market structure: who controls access to the processing infrastructure through which Zimbabwean lithium must pass?
The government therefore needs to balance regulatory certainty with practical implementation. Transitional arrangements, where legally authorised, should be transparent, time-bound and linked to measurable progress towards compliance. They should not undermine the underlying policy objective, but neither should they force otherwise viable producers out of the market simply because processing infrastructure has not kept pace with the regulatory timetable.
The Industrial Investment Pipeline: Who Is Building Zimbabwe’s Lithium Future?
The scale of investment associated with Zimbabwe’s lithium industry demonstrates the commercial significance of the resource. International mining and processing companies have committed capital to expand extraction, establish concentration facilities and develop more advanced processing infrastructure.
The following project overview reflects the investment and development information.
| Project | Location | Reported investment or development focus | Strategic significance |
|---|---|---|---|
| Arcadia, operated by Prospect Lithium Zimbabwe | Goromonzi, Mashonaland East | Reported investment of approximately US$400 million in refinery expansion; stated capacity of 50,000 tonnes annually | A leading test case for domestic lithium chemical conversion |
| Bikita Minerals | Bikita, Masvingo | Reported cumulative investment of US$400–500 million | Expansion of mining and processing, with chemical conversion planned |
| Kamativi Lithium Mine | Kamativi, Matabeleland North | Reported investment exceeding US$100 million across development phases | Potential additional chemical-processing capacity |
| Sabi Star Lithium | Buhera, Manicaland | Reported investment exceeding US$130 million | Concentrate production and assessment of further processing options |
| Sandawana Mine | Mberengwa, Midlands | Multi-stage development programme | Potential integrated lithium mining and processing complex |
The strategic significance of these projects lies not only in their individual production targets but also in their combined contribution to domestic industrial capacity.
If the investments are completed on schedule, Zimbabwe could develop a more sophisticated lithium-processing base, creating demand for engineering, plant maintenance, laboratory testing, industrial chemicals, transport, construction and specialised technical services.
However, announced investment is not the same as operational capacity. The distinction between planned, financed, under-construction, commissioned and commercially operating facilities must remain clear.
For policymakers, the central performance indicators should include actual processing volumes, plant utilisation, product quality, local procurement, export earnings and the extent to which domestic suppliers participate in the industrial ecosystem.
Lithium and the Macroeconomy: Capturing More Value from Every Tonne
Zimbabwe’s mining sector is a major contributor to economic activity, export receipts and government revenue. The expansion of lithium production and processing therefore has implications that extend well beyond the mining industry.
The case for beneficiation rests on a straightforward economic principle: more advanced processing can increase the value of mineral products exported from the country.
Nevertheless, higher unit prices alone do not guarantee higher national economic returns. The full outcome depends on production costs, energy consumption, imported equipment and chemicals, financing charges, tax arrangements, profit repatriation and the proportion of expenditure retained within the domestic economy.
A meaningful assessment of lithium beneficiation must therefore distinguish between gross export receipts and the net economic value retained by Zimbabwe.
The reported export performance
The source material reports that non-gold mineral export earnings reached US$4.735 billion during January–September 2026, representing an increase of 101.8% over the corresponding period in 2025.
It further attributes US$2.159 billion in export earnings to lithium products, compared with US$1.729 billion from platinum group metals.
These figures indicate a substantial change in the composition of Zimbabwe’s mineral exports. Lithium has become a leading contributor to non-gold mineral earnings, reflecting both the expansion of the sector and the changing economics of mineral production and processing.
The supplied figures are summarised below, subject to reconciliation with official export statistics.
| Mineral category | January–September 2025 | January–September 2026 | Reported 2026 share of non-gold mineral exports |
|---|---|---|---|
| Lithium products | Approximately US$560 million | US$2.159 billion | 45.6% |
| Platinum group metals | US$1.810 billion | US$1.729 billion | 36.5% |
| Other non-gold minerals | US$880 million | US$847 million | 17.9% |
| Total non-gold mineral exports | US$2.346 billion | US$4.735 billion | 100% |
The table suggests that lithium’s share of mineral export earnings has increased sharply at a glance though verified figures will cement the position.
Why processing can increase export value
The strongest economic argument for beneficiation is the potential price premium associated with a more advanced product.
For example, May 2026 realised prices of approximately US$8,751 per tonne for lithium sulphate and US$2,595 per tonne for spodumene concentrate.
On those figures, lithium sulphate achieved a gross price approximately 3.37 times that of the concentrate, equivalent to a price premium of about 237%.
This comparison illustrates the potential value of moving beyond concentrate production. It should not, however, be interpreted as a 237% increase in profit or national value added. The two products differ in composition, processing requirements and potentially their pricing basis. A proper comparison would account for lithium content, product purity, recovery rates, conversion costs, energy use, reagents, transport, capital expenditure and the commercial terms of the respective sales.
The central point remains: domestic chemical processing can create an opportunity for Zimbabwe to capture value that would otherwise be generated in overseas refining facilities.
Whether that opportunity translates into higher national income depends on the efficiency and competitiveness of the processing industry.
Investment, Foreign Exchange and the Limits of Gross Export Growth
According to online sources, the cumulative investment commitments across lithium beneficiation, chemical refining and associated power infrastructure is above US$3.4 billion. It also reports that Zimbabwe recorded a merchandise trade surplus exceeding US$500 million by August 2026.
These claims require confirmation from company disclosures and official balance-of-payments or trade statistics. If substantiated, they would demonstrate the scale of capital associated with the transition towards mineral processing.
Yet foreign investment has a dual character.
In the short term, investment brings capital, equipment, construction activity and employment. In the longer term, the net benefit depends on how much of the resulting income remains in Zimbabwe and how strongly the projects stimulate domestic economic activity.
A refinery may export a high-value product while importing much of its equipment, processing chemicals and technical services. It may also require significant foreign-currency expenditure for debt servicing and imported inputs.
Consequently, a rise in gross export receipts should be assessed alongside net foreign-exchange retention, tax payments, local procurement, wages, reinvested profits and domestic supplier development.
Zimbabwe’s policy objective should not be merely to increase the value of the products crossing its borders. It should be to increase the share of that value retained within the national economy.
The Social Contract: Do Mining Communities Benefit?
The success of lithium beneficiation cannot be measured solely through export statistics, processing capacity or investment announcements. It must also be judged by its effects on the communities that host the mines.
Mining operations can stimulate local economies through employment, construction contracts, transport services, accommodation, retail demand and infrastructure investment. Large-scale projects may also support schools, healthcare facilities, technical training and other community initiatives.
Research carried out by The Business Diary cites significant workforce expansion at Bikita Minerals and substantial direct employment associated with Arcadia and a potential five-year employment contribution of up to 100,000 jobs across the wider lithium value chain.
These figures should be verified and clearly differentiated between direct employment, temporary construction jobs, indirect employment and projected opportunities. A projection covering the wider value chain should not be presented as an established count of permanent jobs.
The quality of employment matters as much as the number of positions created.
If local residents are concentrated in low-skilled roles while technical, engineering and senior management positions are filled predominantly from outside the district, the long-term developmental impact will remain limited. A stronger model would connect mining investment to technical colleges, apprenticeships, engineering programmes and supplier-development initiatives that enable local people and businesses to move into higher-value activities.
Roads, dust and the cost of extraction
Mining can also impose costs that are not reflected in export figures.
Heavy trucks transporting ore and concentrate place pressure on rural roads, increasing maintenance requirements and potentially disrupting access to schools, clinics, markets and agricultural production. Dust from unpaved transport corridors can affect neighbouring households and farms, while poorly managed waste and water use can create additional environmental pressures.
These costs are particularly significant when the economic benefits of mining are concentrated among investors and central institutions while local authorities face the burden of maintaining damaged infrastructure.
The appropriate response is not to reject mining investment, but to ensure that the terms under which it operates recognise its wider economic and environmental footprint.
Binding community-development agreements could establish clear obligations for road maintenance, dust suppression, water protection, local recruitment, skills development and procurement from qualified local businesses. Public reporting should make it possible for residents to distinguish between announced commitments and completed projects.
Corporate social responsibility initiatives and Community Share Ownership Trusts can contribute to local development, but voluntary initiatives are not a substitute for transparent, enforceable obligations.
Artisanal miners and the risk of exclusion
Export restrictions may create additional difficulties for artisanal and small-scale miners who lack the capital and technical capacity to establish their own processing facilities.
If these producers cannot access compliant domestic plants on commercially reasonable terms, they may lose access to formal markets or become more vulnerable to informal trading arrangements.
This is an important policy consideration because mineral beneficiation should widen domestic participation in the value chain rather than concentrate all commercial opportunities in the hands of a small number of large operators.
Shared processing facilities, cooperative arrangements, transparent toll-refining tariffs and technical support could help smaller producers meet regulatory requirements while improving traceability and environmental compliance.
The Global Lithium Market: Opportunity and Exposure
Zimbabwe’s lithium strategy is unfolding within an international market shaped by electric-vehicle demand, energy-storage investment, battery technology and the pace at which new mining and refining capacity comes online.
Lithium prices have historically been volatile. Periods of rapid expansion in supply can depress prices, while production disruptions, stronger demand or changes in inventory levels can produce sharp recoveries.
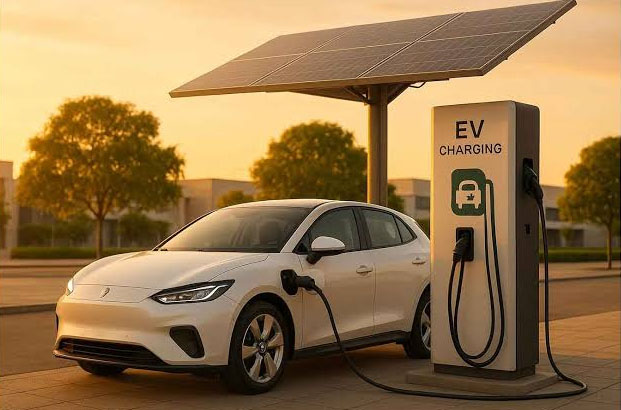
Electric cars have increased demand for lithium worldwide
The source material attributes a stabilisation in lithium carbonate prices during 2026 partly to Zimbabwe’s export restrictions. This is a causal claim that requires particular care.
Zimbabwe’s policies may influence the availability of certain raw materials, especially in markets that depend on Zimbabwean concentrate. However, global lithium prices are also determined by production in other major supplier countries, inventories, refining capacity, battery demand, substitution trends and expectations about future supply.
A change in prices following Zimbabwe’s regulatory intervention does not, by itself, establish that the policy caused the change.
The more defensible conclusion is that Zimbabwe’s beneficiation strategy has the potential to alter the flow of lithium feedstock into international processing markets while increasing the importance of domestic refining capacity.
The country must nevertheless guard against replacing dependence on raw-material exports with dependence on a narrow group of overseas buyers and processing partners.
Diversification of export destinations, investment partnerships and industrial applications would strengthen Zimbabwe’s bargaining position and reduce exposure to changes in the commercial strategies of individual foreign firms.
Resource Nationalism and Africa’s Industrial Policy Debate
Zimbabwe’s approach reflects a broader debate across Africa about how mineral-rich economies can retain more value from their natural resources.
Governments are increasingly examining export restrictions, local-processing requirements, revised mining codes, state participation and domestic industrial investment as potential tools for securing greater economic returns.
The underlying rationale is clear: countries that supply the raw materials required for the energy transition want to participate in the higher-value activities associated with processing, refining and manufacturing.
However, the success of these interventions depends on country-specific circumstances. Export restrictions cannot create competitive processing industries on their own. They must be supported by electricity, transport infrastructure, skilled labour, predictable regulation, access to finance and reliable markets.
For Zimbabwe, the strategic opportunity is to use its lithium deposits as an entry point into a wider industrial ecosystem. This could include chemical manufacturing, mineral-testing laboratories, engineering services, industrial maintenance, logistics, power generation and, over time, selected battery-material applications.
The objective should be to build domestic capabilities that remain economically useful even when commodity prices fluctuate.
The Electricity Constraint: Beneficiation Requires Reliable Power
The most immediate operational risk to Zimbabwe’s beneficiation ambitions is the availability of reliable and competitively priced electricity.
Lithium chemical processing requires energy-intensive industrial operations, including thermal treatment, chemical conversion, material handling and water management. Depending on the process design, interruptions can disrupt production schedules, reduce plant utilisation and increase operating costs.
Currently there is a substantial gap between Zimbabwe’s installed generation capacity and the electricity reliably available to meet national demand. Captive power generation is an increasingly important response among large mining companies.
The underlying challenge, however, is fundamental: a beneficiation policy that requires domestic processing must be accompanied by a credible plan to supply the energy needed to operate the resulting plants.
Captive power and industrial competitiveness
Mining companies are increasingly considering dedicated solar generation, supplementary thermal power, storage and other arrangements to reduce exposure to grid interruptions.
The attraction of captive power is straightforward. A reliable energy supply improves production planning, reduces the risk of operational disruption and can support long-term investment decisions.
Yet private generation also creates additional capital costs. Solar installations may require complementary storage or backup systems to meet continuous industrial demand. Thermal generation introduces fuel costs, emissions and supply risks. Transmission infrastructure and power wheeling arrangements may also affect the economics of alternative electricity sources.
The government can support beneficiation by making it easier for qualified independent power producers to supply industrial customers under transparent, bankable arrangements. Clear rules governing power wheeling, tariffs, grid access and contractual settlement would help mobilise private investment.
The objective should be a more reliable electricity system, not simply a transfer of the power deficit from the public grid to individual mining companies.
Processing Capacity and the January 2027 Deadline
A second challenge is the timing of new processing infrastructure.
Our research identifies Arcadia as an operating lithium-sulphate producer while describing major chemical-processing facilities at Bikita and Kamativi as projects under development.
If additional plants are not commissioned in time to absorb the volumes that would otherwise be exported as concentrate, producers could face a gap between regulatory obligations and available processing capacity.
That gap would have consequences for working capital, storage, production schedules and investment decisions. Smaller operators would be particularly exposed if access to existing refineries were limited.
Before the stated January 2027 deadline, the critical questions are therefore practical;
- How much compliant chemical-processing capacity will be operational, rather than merely announced or under construction?
- What volumes can each facility process, and how much capacity is already committed to its own mine?
- Can third-party producers access available capacity under transparent commercial terms?
- What quality specifications, transport arrangements and environmental requirements must be met?
- What contingency arrangements are legally available if commissioning is delayed?
These questions should be addressed through published capacity assessments and regular industry consultation.
A credible implementation framework would preserve the direction of the beneficiation policy while ensuring that regulatory enforcement is matched by a realistic understanding of industrial readiness.
Strategic Priorities: Turning Mineral Wealth into Lasting Value
Zimbabwe’s lithium strategy presents an opportunity to reshape the relationship between mineral extraction, industrial development and national prosperity. Realising that opportunity will require coordinated action across government, mining companies, energy providers, financial institutions and local communities.
1. Establish accessible processing hubs
The government should assess the feasibility of shared processing facilities or approved industrial hubs serving multiple producers, particularly smaller mining companies.
Where commercially viable, these facilities could offer toll-refining services under published tariffs, transparent quality standards and enforceable service agreements.
Such arrangements would lower the entry barriers associated with standalone chemical plants and broaden participation in domestic beneficiation. Their design should also address capacity allocation, environmental compliance and the financial viability of the facilities themselves.
2. Link beneficiation policy to electricity investment
Reliable power must be treated as an essential component of mineral-industrial policy.
The government should accelerate practical arrangements for independent power producers to supply industrial users, including transparent power-wheeling rules, bankable offtake contracts and investment in appropriate transmission infrastructure.
Energy planning should be based on verified industrial demand forecasts and realistic commissioning schedules. Solar generation, storage, hydroelectricity and other suitable sources should be evaluated according to reliability, cost and environmental performance.
3. Make community benefits measurable and enforceable
Mining communities should have a clearer and more predictable stake in the economic activity taking place around them.
Community-development agreements could specify measurable obligations covering road maintenance, local recruitment, skills development, water protection, dust control and local procurement.
Government should also consider transparent mechanisms through which a defined portion of appropriate mining revenues supports development in producing districts, subject to sound public-finance arrangements and independent oversight.
The central objective is to ensure that the communities bearing the immediate costs of extraction also receive visible and sustainable benefits.
4. Develop local technical skills and suppliers
Domestic beneficiation will generate limited long-term industrial transformation if most high-value technical services, specialised inputs and management expertise continue to be imported.
Mining companies, educational institutions and government agencies should collaborate on training in chemical processing, metallurgy, electrical engineering, instrumentation, environmental management and industrial maintenance.
Supplier-development programmes should help capable Zimbabwean businesses meet the technical, safety and quality standards required by large mining operations.
Over time, these capabilities could support industries beyond lithium, improving the resilience of the wider manufacturing sector.
5. Strengthen mineral governance and revenue transparency
Export restrictions must be accompanied by credible systems for measuring mineral production, verifying export values, monitoring compliance and collecting taxes and royalties.
Transparent reporting would help distinguish legitimate beneficiation investment from speculative announcements and ensure that the public can assess the economic contribution of the sector.
Performance reporting should cover export earnings, net foreign-exchange retention, tax receipts, local procurement, employment quality, environmental compliance and the progress of processing projects.
This would enable government and industry to identify bottlenecks early and adjust implementation without abandoning the strategic objective.
6. Diversify markets and industrial partnerships
Zimbabwe should continue to engage international investors while avoiding excessive dependence on any single market, buyer or technology partner.
Regional integration through the Southern African Development Community and the African Continental Free Trade Area could support trade in mineral products, industrial services and related inputs, where commercially and technically viable.
Partnerships with manufacturers and technology providers across different markets could also widen access to expertise, finance and long-term offtake arrangements.
The goal should be to attract investment on terms that strengthen Zimbabwe’s productive capacity and bargaining position.
Conclusion: Beneficiation Must Deliver More Than Higher Export Prices
Zimbabwe’s lithium strategy represents a significant attempt to move from resource extraction towards a more industrialised mineral economy. The ambition is economically compelling: process more resources at home, capture a greater share of the value chain, strengthen foreign-exchange generation and build capabilities that support wider economic development.
But the success of the strategy will not be determined by export restrictions alone.
It will depend on whether Zimbabwe can build enough competitive processing capacity, provide reliable electricity, maintain predictable regulation, develop local technical expertise and ensure that the benefits of mining extend beyond a limited group of investors and institutions.
Higher export prices are a useful indicator, but they are not the final measure of success. The more meaningful test is whether beneficiation produces greater net economic value for the country through productive investment, skilled employment, domestic enterprise development, public revenue and better living conditions in mining communities.
Zimbabwe’s lithium deposits offer a valuable industrial opportunity. Converting that opportunity into lasting prosperity requires a policy framework that is firm in its direction, realistic in its implementation and transparent in the distribution of its returns.
The ultimate measure of success will not be how much lithium Zimbabwe extracts or how much refined material it exports. It will be how effectively the country converts a finite geological resource into enduring economic capability.
Mining & Minerals
Mining, Community and the New CSR Compact in Zimbabwe’s Gold Sector: Better Brands at Penhalonga


Zimbabwe’s Property Investment Boom: Local Capital Reshapes the Commercial and Residential Landscape

Zimplats Hands Over to Segula as Mhembere Retires After 19 Years and Two Directors Join the Board

Zimbabwe’s 2027 Budget: What Business Leaders Should Watch Before 19 November

What is Robert Kiyosaki’s net worth after his latest book flop?

Egypt’s Richest Man, Nassef Sawiris’ Wealth Surges by $410M in Just over a Week.

Billionaires Who Didn’t Go to College
-
 Business & Economy3 years ago
What is Robert Kiyosaki’s net worth after his latest book flop?
-
Business & Economy3 years ago
Egypt’s Richest Man, Nassef Sawiris’ Wealth Surges by $410M in Just over a Week.
-
Business & Economy3 years ago
Billionaires Who Didn’t Go to College
-
Business & Economy3 years ago
Africa’s youngest billionaire: Mo Dewji’s impactful empire extends beyond wealth
-
Business & Economy3 years ago
Meet World’s Richest Family Who live In $478m House, Own 700 Cars
-
Technology & Telecommunications3 years ago
Liquid C2 partners with Google Cloud and Anthropic to bring advanced cloud, cyber security and generative AI capabilities to Africa
-
Business & Economy3 years ago
Zimbabwe’s Beverage Industry: A Digital Marketing Analysis of Delta Beverages and Varun Beverages Zimbabwe
-
Business & Economy3 years ago
Malawian Billionaire Thom Mpinganjira’s Fortune Drops by $8 Million in a Month